NEWS
“This Is the Wrong Time to Impose New Taxes” — Finance Minister, Taiwo Oyedele Warns Governments Against Increasing Tax Burden on Nigerians

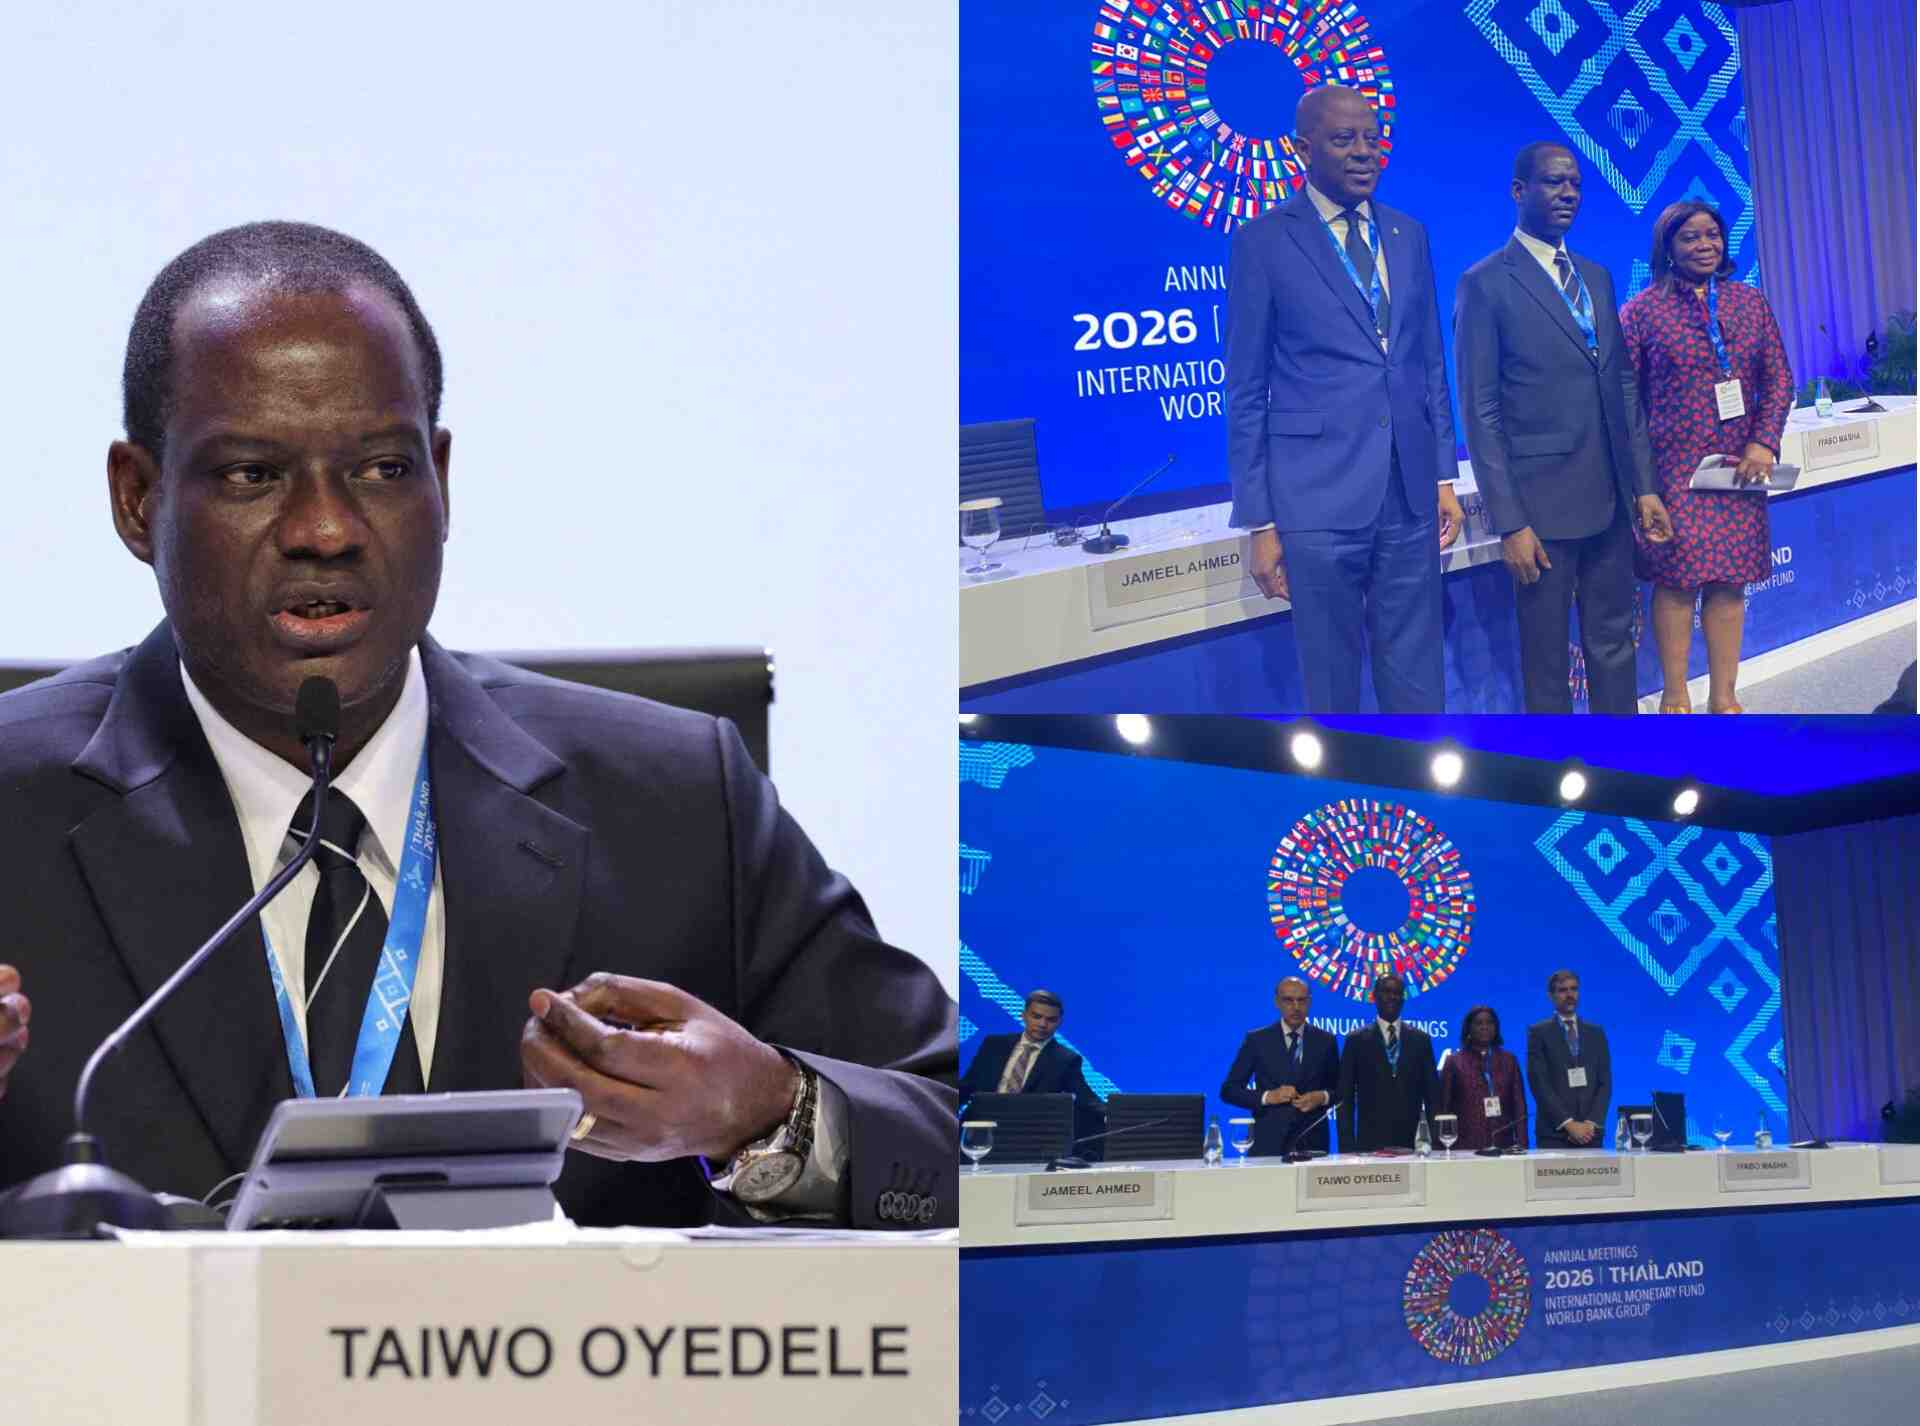
Nigeria’s Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, has warned governments against introducing new taxes or increasing existing tax burdens on vulnerable populations and productive sectors of the economy, stressing that the current economic climate demands policies that protect citizens while supporting businesses and economic growth.
Oyedele made the position known on the sidelines of the 2026 annual meetings of the International Monetary Fund (IMF) and the World Bank in Bangkok, Thailand, where he presented the communiqué of the Intergovernmental Group of Twenty-Four (G24).
The minister’s remarks highlighted the need for governments, particularly in developing economies, to adopt a balanced approach to revenue generation, debt management and public expenditure without imposing additional financial hardship on households and businesses already facing economic pressures.
“This is the wrong time to impose new taxes or increase the tax burden, particularly on vulnerable populations and productive sectors of the economy,” Oyedele said.
He explained that while governments must mobilise sufficient revenue to fund public services and meet their financial obligations, such efforts should not undermine the welfare of citizens, discourage business activities or weaken the productive capacity of their economies.
According to the minister, developing countries seeking to reduce the cost of servicing their debts without cutting essential public spending must first examine their domestic financial management systems, identify wasteful expenditure and explore opportunities to improve revenue collection.
Responding to a question on how governments could reduce debt-servicing costs while maintaining critical services, Oyedele emphasised that countries should look inward for savings and strengthen revenue mobilisation strategies rather than place additional financial demands on citizens and businesses.
“The measures, as you asked, would first involve every country looking inward to identify areas for savings and revenue mobilisation, while bearing in mind that this is the wrong time to impose new taxes or increase the tax burden, particularly on vulnerable populations and productive sectors of the economy,” he said.
His position underscores the importance of improving public financial management, tackling inefficiencies and ensuring that existing revenue sources are administered effectively before governments consider measures that could further strain household incomes or increase the operating costs of businesses.
Oyedele also defended the role of borrowing in financing economic development, arguing that debt should not automatically be viewed as a negative instrument. Instead, he said governments must ensure that borrowed funds generate meaningful economic benefits, create employment opportunities and promote inclusive growth.
“Borrowing and debt financing are necessary conditions for growth, and every emerging and developing country must be able to use debt financing in a way that has an overall positive impact, particularly by stimulating job-rich and inclusive growth,” he said.
The finance minister maintained that borrowing could support economic expansion when directed towards productive investments capable of strengthening national economies and improving living standards.
However, his remarks also point to the importance of ensuring that loans are deployed responsibly, with clear development objectives and the capacity to deliver economic returns that justify the cost of borrowing.
On public spending, Oyedele said governments should prioritise essential services, particularly healthcare and education, when allocating limited public resources. He noted that public financing constraints make it necessary for governments to identify areas where private capital could complement public investment and help meet broader development needs.
The approach, he suggested, would allow governments to preserve funding for critical social services while exploring alternative financing arrangements for other sectors of the economy.
Addressing the debate over whether governments should rely more heavily on taxation or borrowing, Oyedele cautioned against treating the two financing options as mutually exclusive. He explained that taxation has immediate consequences for household purchasing power and business operations, while borrowing creates obligations that future governments and taxpayers must ultimately manage.
“If you collect taxes, you raise the money now, and that itself has a lot of trade-offs. What taxes are you collecting? If you collect taxes from the most vulnerable, you deprive them of money to provide food, healthcare and education,” he said.
The minister stressed that tax policies must take into account the economic circumstances of those expected to pay, particularly low-income households whose limited resources are often directed towards basic necessities.
He further explained that excessive taxation of vulnerable citizens could reduce their ability to afford essential goods and services, potentially worsening hardship and undermining broader development objectives.
Oyedele also highlighted the long-term implications of borrowing, noting that debt obligations eventually place demands on future public revenue. He said governments must therefore strike a careful balance between raising revenue through taxes and obtaining financing through debt.
According to him, the ultimate objective of both approaches should be to improve the welfare of citizens and ensure that public resources are used in ways that benefit society.
“Debt is future taxes, so it’s not one or the other. It’s about striking a balance, bearing in mind that, ultimately, the purpose of taxation and borrowing is to cater for the people.”
The minister’s comments come amid continuing discussions among developing economies about rising debt-servicing costs, limited fiscal space, revenue mobilisation and the need to sustain public investment without deepening economic hardship.
For many developing countries, a significant portion of government revenue is committed to servicing existing debts, leaving less money available for infrastructure, education, healthcare and social protection. The challenge is particularly pronounced where governments must simultaneously address economic vulnerabilities, expand employment opportunities and maintain essential public services.
The 2026 IMF and World Bank annual meetings, which are holding from October 12 to October 18 in Bangkok, Thailand, have brought together delegations from more than 190 countries to discuss international economic developments, financial stability and policy options for addressing global and domestic economic challenges.
Nigeria’s delegation includes chief executive officers of financial institutions, private-sector representatives, civil society organisations, non-governmental organisations and other stakeholders.
The meetings provide an important platform for governments and international financial institutions to examine strategies for strengthening economic resilience, improving fiscal management and addressing the financial challenges confronting developing economies.
The IMF, as part of its longstanding mandate, provides economic policy advice, monitors member countries’ economies and offers financial assistance to countries experiencing balance-of-payments difficulties. The World Bank also plays a major role in supporting development initiatives and financing projects aimed at reducing poverty and improving living standards.
Oyedele’s intervention at the meetings reinforces the argument that effective economic management requires more than simply increasing taxes or accumulating debt. Governments must also improve spending efficiency, strengthen revenue administration, protect vulnerable citizens and ensure that public borrowing supports productive economic activity.
His central message is that revenue generation and debt management should ultimately serve the people, rather than impose unsustainable financial pressure on households and busi
 nesses or undermine the foundations of economic growth.