
NEWS
FG Introduces New Interest Regime for Late Tax Payments, Links Rates to Market Benchmarks

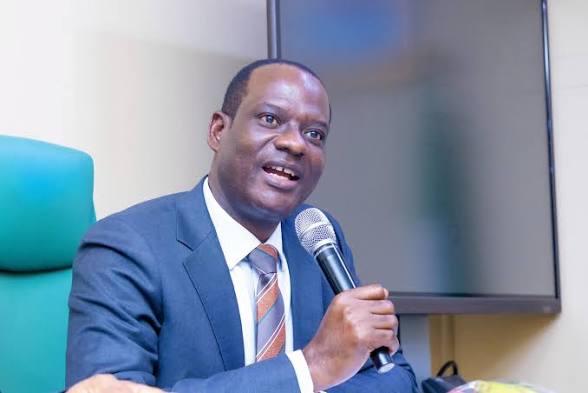
— Takes Effect From October 1, 2026.
The Federal Government has introduced a new framework for calculating interest on overdue tax liabilities, with the Nigeria Tax Administration Order 2026 scheduled to take effect from October 1, 2026.
The new framework, signed by the Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, is designed to align the financial consequences of late tax payments more closely with prevailing market conditions and the cost of government borrowing.
Under the new arrangement, taxpayers with outstanding tax liabilities denominated in naira will be charged interest at the Central Bank of Nigeria’s Monetary Policy Rate plus one percentage point.
However, the applicable interest rate will not fall below the yield on 364-day Nigerian Treasury Bills. This provision reflects the government’s position that delayed tax revenue creates a financing gap that may have to be covered through borrowing.
For tax obligations denominated in foreign currencies, the interest rate will be calculated using the Secured Overnight Financing Rate, or SOFR, plus six percentage points.
SOFR is a widely recognised benchmark for US dollar-denominated borrowing. The Order further provides that if SOFR is discontinued, its officially recognised successor benchmark will be adopted for the purpose of calculating interest on the affected tax liabilities.
The Federal Government said the new framework is intended to ensure that taxpayers do not gain a financial advantage by retaining tax payments beyond their due dates.
Explaining the rationale behind the policy, Oyedele said, “Tax that is due belongs to the public. When it is paid late, Government may have to borrow to fill the gap, and the cost falls on everyone.”
According to the minister, tying interest on overdue taxes to prevailing market rates would discourage taxpayers from effectively using unpaid tax obligations as a cheaper alternative to obtaining legitimate financing from the market.
The policy also introduces a more predictable system for taxpayers by requiring the Nigeria Revenue Service to publish the applicable interest rate for every calendar month.
Under the Order, the Nigeria Revenue Service is expected to publish the relevant rate on its website by the third business day of each month, allowing taxpayers to determine in advance the interest that could apply to outstanding liabilities.
Oyedele said the arrangement would also promote consistency and transparency in tax administration across the country.
“Every taxpayer, whether dealing with the Nigeria Revenue Service or a State revenue service, will know the rate in advance, see it published every month, and be charged in the same way,” he said.
The new interest rates will apply to interest arising from October 1, 2026. This includes interest relating to tax liabilities that became due before the commencement date, although interest that accrued before October 1 will continue to be governed by the rules applicable during the period in which it accrued, where the existing regulations specifically provide for that treatment.
The 2026 Order effectively replaces the 2017 notice on interest payable on unpaid taxes, alongside other earlier notices dealing with the calculation of interest on overdue tax liabilities.
The Federal Government, however, clarified that the new framework does not abolish or modify the separate penalty for late payment of tax.
Specifically, the 10 per cent penalty prescribed under Section 65 of the Nigeria Tax Administration Act, 2025, remains in force. The interest regime therefore operates alongside the statutory penalty rather than replacing it.
Tax authorities will also continue to exercise the power provided under Section 66 of the Act to waive penalties or interest where a taxpayer is able to establish sufficient cause.
The government said the framework is ultimately aimed at strengthening compliance while providing taxpayers with a clear and publicly accessible method for determining the financial implications of delayed tax payments.
Oyedele consequently urged taxpayers to submit their tax returns on time and settle their liabilities promptly to avoid additional financial costs.
He also advised taxpayers with existing outstanding liabilities to either settle their obligations or engage the relevant tax authority to address their tax position.
Taxpayers were further encouraged to regularly monitor the Nigeria Revenue Service website for the monthly interest rates applicable under the new framework, particularly as the rates will be linked to prevailing financial-market benchmarks and may therefore change over time.